
How to Cancel or Surrender Your GST Registration Online: A Complete Guide
Are you closing your business, changing its structure, or has your turnover fallen below the GST threshold? Just as obtaining a GST registration is a key milestone, knowing how to cancel GST registration online properly is crucial for compliance. Closing your books isn’t just about ceasing operations; it involves formally notifying the government that you will no longer be collecting or paying Goods and Services Tax. This formal process of canceling your GSTIN (Goods and Services Tax Identification Number) must be followed diligently to avoid future liabilities, penalties, and legal complications that can arise from an active but unused registration. This comprehensive guide provides a clear roadmap on how to manage the GST registration cancellation procedure India, designed specifically for small business owners, freelancers, and entrepreneurs. We’ll break down every step, ensuring you can navigate the GST portal with confidence. And if you need help, TaxRobo is always here to assist.
When and Why Should You Cancel Your GST Registration?
Understanding the circumstances under which you can or must cancel your GST registration is the first step toward compliance. The decision to surrender your GSTIN is not arbitrary; it is governed by specific rules and eligibility criteria under the GST Act. This section of our surrendering GST registration guide India will help you determine if cancellation is the right and necessary step for your business at this time. It’s essential to differentiate between a choice and a requirement, as this impacts the entire process.
Who is Eligible for GST Cancellation?
The GST law provides for two distinct methods of cancellation, each initiated by a different party for different reasons. Understanding which category you fall into is fundamental to navigating the procedure correctly.
- Voluntary Cancellation: This is when the registered person, such as a business owner or proprietor, decides to initiate the cancellation process themselves. This article primarily focuses on this voluntary procedure, which is the most common scenario for businesses that are closing down or whose operations have changed significantly. You are eligible for voluntary cancellation if you meet one of the reasons listed in the next section.
- Suo Moto Cancellation: This type of cancellation is initiated by a proper tax officer. It is not a voluntary act but rather a consequence of non-compliance. An officer may proceed with suo moto cancellation if a taxpayer has, for example, failed to file GST returns for six consecutive months, has not commenced business within six months of registration, or has obtained the registration through fraud or misrepresentation. This is a forced cancellation and often comes with scrutiny and potential penalties.
Top Reasons for Surrendering GST Registration
If you are considering voluntary cancellation, your reason must align with the provisions of the GST Act. Here are the most common and valid reasons for which a taxpayer can apply to cancel GST registration online:
- Discontinuation or Closure of the Business: This is the most straightforward reason. If you have permanently shut down your business operations, you are no longer required to be registered under GST.
- Transfer of Business: When a business is transferred fully, whether through a sale, merger, demerger, amalgamation, or lease, the original owner’s GST registration must be canceled. The new owner must obtain a fresh GST registration.
- Change in the Constitution of the Business: This occurs when the legal structure of your business changes, leading to a change in your PAN. For instance, if a sole proprietorship is converted into a partnership firm or a private limited company, the proprietorship’s GSTIN must be canceled, and a new registration must be obtained for the new entity.
- Turnover Below the Threshold: If you obtained GST registration voluntarily and your aggregate turnover remains below the mandatory registration threshold (e.g., ₹40 lakh for goods and ₹20 lakh for services, with variations for special category states), you can opt to cancel your registration.
- No Longer Liable for Registration: This applies to situations where a change in law or business circumstances means you are no longer required to be registered. For example, if a product you exclusively deal in becomes exempt from GST.
- Death of a Sole Proprietor: In the unfortunate event of the death of a sole proprietor, the legal heirs must apply for cancellation of the GST registration. If the business is to be continued, the heir must first apply for a new registration in their name.
Pre-Cancellation Checklist: 3 Things You Must Do First
Before you even log in to the GST portal to begin the cancellation process, there are critical preparatory steps you must take. Skipping this groundwork is the most common reason for application rejection and delays. Completing this checklist ensures your application is processed smoothly and prevents future compliance issues. Think of it as closing your financial accounts properly before shutting the door.
1. Clear All Pending Liabilities
The GST system is designed to ensure that no taxpayer can exit the system while having outstanding dues. Before you submit your cancellation application, you must clear every single pending liability. This includes any unpaid tax, accumulated interest on late payments, late fees for delayed return filing, or any penalties that have been levied against your GSTIN. The portal has built-in checks that will prevent you from proceeding if your electronic liability register shows any outstanding amount. Ensure you have paid all dues through the appropriate challans and that your account reflects a zero balance.
2. File All Pending GST Returns
This is a non-negotiable prerequisite. The GST portal will not allow you to file Form GST REG-16 (the cancellation application) if you have any pending GST returns. You must file all your GSTR-1 (details of outward supplies) and GSTR-3B (summary return) forms up to the date you intend to apply for cancellation. For taxpayers under the QRMP scheme, all relevant returns must be up to date. This ensures that the government has a complete record of your transactions up until the point of your proposed exit, which is essential for verifying your final tax liability.
3. Account for Stock and Input Tax Credit (ITC)
When you cancel your GST registration, you are essentially transitioning from a taxable person to a non-taxable person. Therefore, the government needs to ensure that you do not unduly benefit from the Input Tax Credit (ITC) you claimed on goods that are still with you. Before applying for cancellation, you must:
- Take a detailed inventory of your closing stock. This includes raw materials (inputs), work-in-progress (semi-finished goods), finished goods, and capital goods.
- Calculate the ITC that you have claimed on this closing stock. This credit must be reversed.
- You will be required to pay an amount equivalent to the ITC claimed on your closing stock or the output tax payable on those goods, whichever is higher. This amount can be paid by debiting your electronic credit ledger or electronic cash ledger. This step ensures that tax is paid on the goods that will now exit the GST system along with your registration.
The Step-by-Step Guide to Cancel GST Registration Online
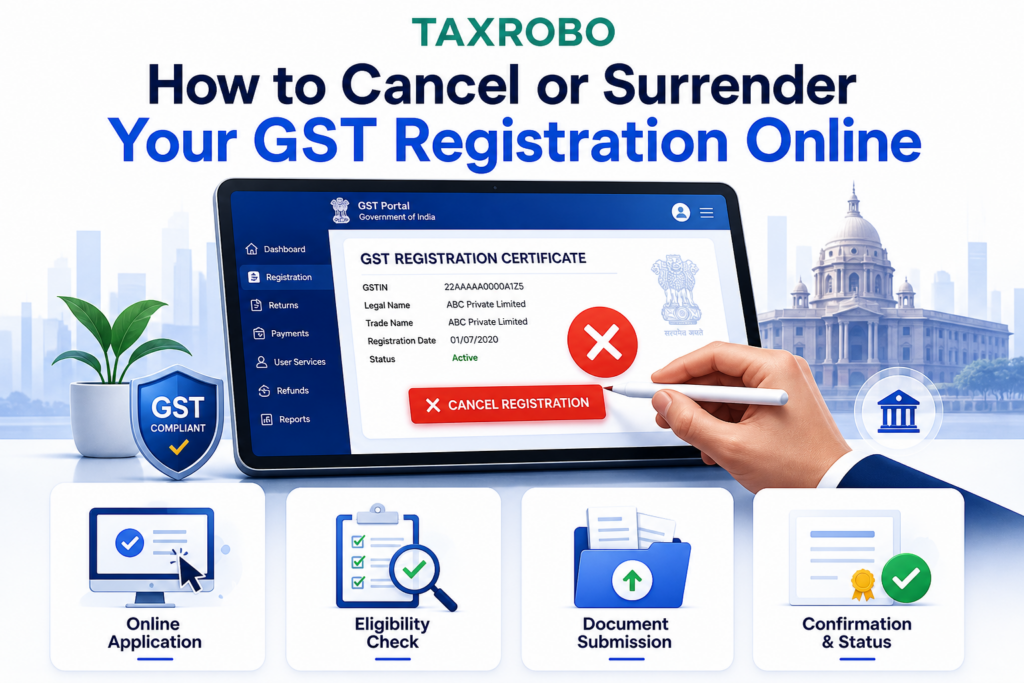
Once you have completed the pre-cancellation checklist, you are ready to begin the formal steps to cancel GST registration online. The process is handled entirely through the official GST portal, using a form named GST REG-16. Following this GST registration cancellation procedure India meticulously will ensure your application is submitted correctly.
Step 1: Log in to the Official GST Portal
First, navigate to the official GST Portal at www.gst.gov.in. Use your unique username and password to log in to your taxpayer dashboard.
- Actionable Tip: Ensure you have access to the mobile number and email address registered with your GSTIN. You will need them to receive the One-Time Password (OTP) required for authenticating your submission.
Step 2: Navigate to the Cancellation Application Form
Once you are logged into your dashboard, you need to find the correct application form. Follow this navigation path carefully:
Services > Registration > Application for Cancellation of Registration
Clicking on this link will take you directly to the application form, GST REG-16.
Step 3: Fill Out Form GST REG-16
This form is the core of your cancellation request. It has several sections that you need to fill out accurately.
- Basic Details: The first part of the form will be auto-populated with your business’s legal name, trade name, and address. You will need to confirm or fill in the address for future correspondence.
- Reason for Cancellation: This is a crucial field. From the dropdown menu, select the reason that most accurately reflects your situation (e.g., ‘Discontinuation of business’, ‘Change in constitution of business’, etc.). Based on your selection, further fields may appear.
- Date of Cancellation: You must specify the date from which you want the cancellation to be effective. This date should be after you have ceased all taxable activities.
- Details of Stock: Here, you will declare the value of the closing stock you have on hand as of the cancellation date. You must enter the value of inputs, semi-finished goods, finished goods, and capital goods. The system will also require you to enter the corresponding Input Tax Credit (ITC) associated with this stock, which you are liable to reverse or pay.
- Details of Recipient (if business transferred): If your reason for cancellation is the transfer, merger, or sale of your business, you must provide the GSTIN of the new entity to which the business has been transferred.
Step 4: Verify and Submit the Application
After filling in all the required details, the final step is to verify and submit the form. The GST portal provides two methods for authentication:
- With Digital Signature Certificate (DSC): This method is mandatory for all Public and Private Limited Companies, Limited Liability Partnerships (LLPs), and Foreign Companies/LLPs.
- With Electronic Verification Code (EVC): For all other taxpayers, including sole proprietorships and partnership firms, you can verify using an EVC. An OTP will be sent to your registered mobile number and email address, which you must enter to complete the submission.
Upon successful submission, an Application Reference Number (ARN) will be generated and sent to you via SMS and email. You can use this ARN to track the status of your cancellation application.
What Happens After You Apply for Cancellation?
Submitting Form GST REG-16 is not the end of the surrender GST registration process India. Your application now enters a review stage, and there are further compliance steps you must take to finalize the closure of your GSTIN. Understanding this post-application phase helps you stay prepared and responsive.
The Officer’s Review
Once your application is submitted, a proper tax officer will examine it. The officer is tasked with verifying the reasons you’ve provided and ensuring all your liabilities have been settled. This review process must be completed within 30 days of your application submission. During this period, two outcomes are possible:
- Approval: If the officer is satisfied with your application and finds no discrepancies, they will issue a formal cancellation order in Form GST REG-19. The date of cancellation mentioned in this order will be the effective date your GSTIN becomes inactive.
- Clarification Required: If the officer finds any issues, such as incomplete information or pending dues, they will issue a show-cause notice in Form GST REG-17. This notice will detail the discrepancies and ask you to provide a clarification or furnish additional documents. You must reply to this notice in Form GST REG-18 within 7 working days. Failure to respond satisfactorily may lead to the rejection of your application.
Filing Your Final Return: Form GSTR-10
This is arguably the most critical and often-overlooked step in the entire cancellation process. Once you receive the cancellation order (Form GST REG-19), your compliance duties are not yet over. You are legally required to file a “Final Return” using Form GSTR-10.
- What is GSTR-10? This return is a final statement of your stock held on the day before your cancellation became effective. It serves as a final declaration of your assets and the tax liability related to them, ensuring that all ITC on remaining stock is correctly reversed.
- Crucial Deadline: You must file Form GSTR-10 within three months from the date of cancellation or the date of the cancellation order, whichever is later. For example, if your cancellation order is issued on October 15th for a cancellation effective from September 30th, you must file GSTR-10 by January 15th.
Conclusion
Canceling your GST registration is a formal process that requires careful attention to detail, from initial preparation to final compliance. By clearing all your dues, filing pending returns, accurately maintaining accurate accounting records for your stock, and correctly submitting Form GST REG-16, you can ensure a smooth and hassle-free process. Remember, the journey doesn’t end with the application; filing the mandatory final return, GSTR-10, is the last and most crucial step to officially close your GST obligations. Following this guide makes it easy to cancel GST registration online and maintain full compliance with Indian tax laws, protecting you from future penalties and notices.
The surrender GST registration process India can feel complex, with multiple forms and strict deadlines. If you want to ensure it’s done right the first time without any hassle, contact the experts at TaxRobo today. We handle the entire process for you, from liability assessment to final return filing, so you can focus on your next venture with complete peace of mind.
Frequently Asked Questions (FAQs)
Q1: Can I file GST returns after applying for cancellation?
Answer: Yes, you are absolutely required to continue filing your regular GST returns (like GSTR-1 and GSTR-3B) for the period until your cancellation application is officially approved and the final cancellation order is issued by the tax officer. Ceasing to file returns after applying for cancellation but before approval will lead to non-compliance, late fees, and potential rejection of your application.
Q2: What happens if I don’t file the final return (GSTR-10)?
Answer: Failure to file GSTR-10 within the specified three-month period is a serious compliance lapse. The GST department will first issue a notice, giving you 15 days to file the return. If you still fail to comply, you will be liable for a penalty of ₹200 per day of delay (₹100 for CGST and ₹100 for SGST), subject to a maximum of ₹10,000.
Q3: What is the time limit for applying for GST cancellation?
Answer: You must apply for cancellation in Form GST REG-16 within 30 days of the “event of cancellation.” This means you have 30 days from the date you close your business, transfer your business, or become no longer liable for registration to submit your application.
Q4: Can I reactivate my GST registration after it has been voluntarily canceled?
Answer: No. Once a GST registration has been voluntarily canceled by the taxpayer, it is a permanent closure. It cannot be revoked or reactivated. If your business circumstances change and you once again become liable to register for GST, you must go through the entire process of applying for a completely new GST registration. The concept of revocation only applies to registrations that were canceled by a tax officer (suo moto cancellation).