
Freelancer to Founder: When Your Side Hustle Legally Becomes a Business
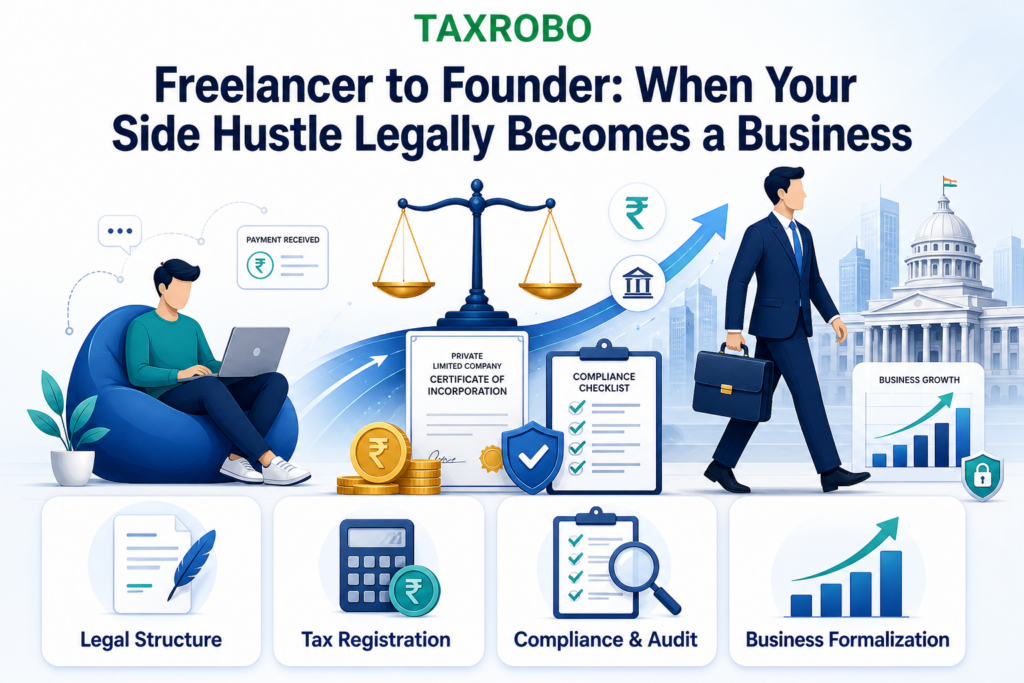
Your freelance gig or passion project is thriving. What started as a small side hustle to earn extra income now has a steady stream of clients, growing revenue, and takes up a significant chunk of your time. This success brings you to a critical crossroads in your journey from freelancer to founder. The question is no longer if you should formalize your venture, but when and how. Many talented entrepreneurs in India find themselves in this exciting but confusing position, unsure about the specific legal triggers that transform a casual hustle into a formal business. This guide breaks down the key milestones and legal steps for transitioning from freelancer to founder, ensuring your growing business is compliant, protected, and ready to scale. We’ll cover the definitive signs that your side hustle is now a business, the different legal structures you can choose from, and the essential registrations you need to complete.
The Tipping Point: 4 Signs Your Side Hustle is Legally a Business in India
Recognizing the right moment to formalize is the first step in your freelancer to founder journey. While there’s no single switch that flips, certain milestones act as clear indicators. Here are the key signs to watch for based on Indian side hustle regulations that tell you it’s time to register your business.
1. Your Annual Turnover is Approaching the GST Threshold
The most definitive and non-negotiable sign is your revenue. The Goods and Services Tax (GST) law in India has clear turnover limits. Once your gross annual revenue crosses these thresholds, you are legally required to register for GST. Ignoring this can lead to significant penalties.
- For Service Providers: If your annual turnover from services exceeds ₹20 lakhs, GST registration is mandatory.
- For Sellers of Goods: If your annual turnover from selling goods exceeds ₹40 lakhs, GST registration is mandatory.
- Special Category States: For certain states in the North-East and hilly regions, this threshold is lower at ₹10 lakhs for services and ₹20 lakhs for goods.
It is crucial to understand that this turnover includes all revenue generated from your side hustle activities across India, even if you are a salaried employee. Proactively monitoring your income is essential, as this is the most critical factor in a side hustle becoming a business in India in the eyes of the law. You can check the latest thresholds and state-wise lists on the official GST Portal.
2. Your Operations Have Become Consistent and Organized
From the Income Tax Department’s perspective, a “business” is often defined by its intent, regularity, and organized nature. A one-off project might be considered a hobby, but consistent activity with a clear goal of earning is a business. Ask yourself if your hustle exhibits the following characteristics:
- Profit Motive: Is your primary intention to make a profit, rather than just pursuing a hobby?
- Regularity of Transactions: Are you invoicing clients or making sales on a frequent and consistent basis (e.g., weekly or monthly) rather than sporadically once or twice a year?
- Separate Records: Have you instinctively started maintaining a separate spreadsheet for your business expenses, or even opened a separate bank account to keep your hustle’s finances apart from your personal funds?
If you answered yes to these questions, you are already operating with the intent and structure of a business, and it’s wise to formalize it to manage your finances and taxes correctly.
3. You Plan to Hire Employees or Full-Time Contractors
The moment you decide to bring someone on board to help manage the workload, you are making a significant leap. Hiring your first employee, or even engaging a contractor on a full-time, dedicated basis, is a clear signal that your operation has scaled beyond a solo gig. This step comes with immediate legal responsibilities.
Hiring triggers several compliance requirements that are mandatory for businesses, not individuals. You will need to:
- Obtain a TAN (Tax Deduction and Collection Account Number) to deduct TDS (Tax Deducted at Source) from employee salaries or contractor payments.
- Potentially register for Provident Fund (PF) and Employee’s State Insurance (ESI) depending on the number of employees.
Managing payroll and its associated compliances requires a formal business structure.
4. You Are Seeking External Funding or Bank Loans
If your ambitions involve scaling rapidly, you might consider seeking investment from angel investors, venture capitalists, or applying for a business loan from a bank. This is a pivotal moment in freelancing to entrepreneurship in India. No investor or financial institution will inject capital into an individual’s personal bank account. They require a formal, registered business entity for several reasons:
- Liability Protection: Investors need assurance that their investment is in a separate legal entity, like a Private Limited Company, which offers limited liability.
- Formal Structure: A registered company has a formal shareholding structure that allows for equity distribution.
- Credibility and Due Diligence: A registered entity is seen as more credible, transparent, and easier to conduct due diligence on.
If funding is on your roadmap, registering your business is not just a legal step—it’s a strategic necessity.
Your Legal Roadmap: How to Start a Business From a Side Hustle
Once you’ve identified the signs and decided to make the leap, you need a clear plan. Here is the step-by-step legal roadmap to guide your transition from freelancer to founder and successfully register your new business.
Step 1: Choose the Right Business Structure
Selecting the right legal entity is the foundational decision for your business. It impacts your liability, compliance burden, and ability to raise funds. Choosing the Right Legal Structure for Your Business is a critical first step. Here’s a comparison of the three most common structures for new founders in India.
| Feature | Sole Proprietorship | One Person Company (OPC) | Private Limited Company (Pvt. Ltd.) |
|---|---|---|---|
| Legal Status | You and the business are one and the same | Separate legal entity from its owner | Separate legal entity from its shareholders |
| Liability | Unlimited: Your personal assets are at risk. | Limited: Personal assets are protected. | Limited: Personal assets of shareholders are protected. |
| Startup Cost | Very Low (Minimal to no registration cost) | Moderate (Requires MCA registration) | High (Requires MCA registration and more formalities) |
| Compliance | Minimal (Only Income Tax filing) | Moderate (ITR filing, annual MCA filings) | High (ITR, GST, MCA filings, board meetings, audits) |
| Fundraising Ability | Difficult | Possible, but must convert to Pvt. Ltd. after funding. | Easy to raise funds by issuing shares. |
| Best For | Solo freelancers, consultants, small local stores | Solo entrepreneurs wanting limited liability and credibility | Startups planning to scale, hire employees, and seek funding |
Step 2: Complete the Essential Business Registrations
After choosing your structure, the next phase involves securing the necessary registrations. This is the core of the business side hustle registration India process.
- Company/Business Registration:
- Sole Proprietorship: There is no formal registration for a proprietorship itself. Its existence is established through other registrations like GST or a bank account.
- OPC/Pvt. Ltd.: These entities must be incorporated with the Ministry of Corporate Affairs (MCA). This process involves obtaining a Director Identification Number (DIN) for the director(s) and a Digital Signature Certificate (DSC) for signing electronic forms. For a complete walkthrough, see our guide on How to Register a Company in India: Complete Process & Checklist. You can start the process on the official MCA website.
- PAN and TAN:
- While a proprietorship uses the owner’s personal PAN, an OPC and a Private Limited Company must apply for a separate business PAN card.
- A TAN (Tax Deduction and Collection Account Number) is mandatory for any business that is required to deduct TDS, which is common when paying salaries, contractor fees, or rent.
- GST Registration:
- As discussed earlier, this is mandatory if your turnover crosses the prescribed limit. It is also mandatory irrespective of turnover if you are making inter-state sales, selling through an e-commerce platform, or fall under certain other categories. You can learn more from our Ultimate Guide to GST Registration for Small Businesses.
- MSME/Udyam Registration:
- While not always mandatory, registering your business as a Micro, Small, or Medium Enterprise (MSME) on the Udyam portal is highly beneficial. It gives you access to government schemes, priority sector lending from banks, and easier access to credit.
Step 3: Set Up Your Financial Foundation
A clear separation between personal and business finances is a non-negotiable trait of a serious founder. This financial discipline is crucial for accurate accounting, tax compliance, and legal protection.
- Open a Current Bank Account: Once you have your registration documents, immediately open a business current account. All business income should be deposited into this account, and all business expenses should be paid from it. For an OPC or Pvt. Ltd., this is a legal requirement.
- Understand Your Tax Obligations: Your tax filing process will change. As a freelancer, you likely filed ITR-3 or ITR-4. A Private Limited Company files its own corporate tax return. For proprietorships or single founders, explore the Presumptive Taxation Scheme under Section 44AD (for businesses) or 44ADA (for professionals), which allows you to declare profits as a percentage of your turnover, simplifying tax compliance.
- Implement an Invoicing System: Ditch the informal payment requests. Use professional invoicing software to create GST-compliant invoices. This not only looks professional but is also a legal requirement for tracking sales and filing GST returns.
Protecting Your New Venture: IP and Ongoing Compliance
Safeguard Your Brand with Trademark Registration
As your business grows, your brand name, logo, and tagline become your most valuable assets. They are how customers recognize you. A trademark registration grants you the exclusive legal right to use your brand identity for the goods or services you offer. It prevents competitors from using a confusingly similar name or logo, protecting your reputation and market share. This is a crucial step in building long-term brand equity and value in your enterprise.
Stay on Top of Annual Compliances
Running a registered business comes with recurring responsibilities. Staying on top of these legal requirements for business India is essential to avoid penalties and maintain your company’s active status. Key annual compliances include:
- Annual ITR Filing: Every business, regardless of its structure, must file an annual income tax return.
- GST Returns: Depending on your turnover and registration type, you will need to file monthly, quarterly, and/or annual GST returns.
- MCA Annual Filings (for OPC/Pvt. Ltd.): Companies must file annual returns and financial statements with the Registrar of Companies (ROC). Failure to do so can result in heavy penalties and even the company being struck off the register.
Conclusion
The journey from freelancer to founder is an exciting and empowering step that signifies true entrepreneurial growth. The transition from a casual side hustle to a formal business is marked by clear triggers like crossing revenue thresholds, hiring staff, or seeking investment. By understanding these signs, choosing the right legal structure like a Sole Proprietorship, OPC, or Private Limited Company, and diligently completing key registrations (GST, PAN, MCA), you lay a strong legal and financial foundation for your venture. While it involves navigating legal formalities, this process provides your business with credibility, liability protection, and the framework for sustainable success.
Ready to make your side hustle official? Don’t let paperwork and legal complexities hold you back. The experts at TaxRobo specialize in helping entrepreneurs with everything from company registration to GST filing and annual compliances. Contact us today for a consultation and take the first real step in your journey from freelancer to founder in India!
Frequently Asked Questions (FAQs)
1. Can I continue using my personal bank account for my business?
While it is technically possible for a Sole Proprietorship, it is highly discouraged. Opening a separate business current account is crucial for clean bookkeeping, accurately tracking your profitability, and appearing professional to clients. Mixing personal and business funds can create significant confusion during tax filing. For an OPC or Private Limited Company, a separate bank account is mandatory by law.
2. Do I need a physical office to register my business?
No, you do not need a commercial office space. You can use your home address as the registered office address for your company. To do this, you will typically need to provide a No Objection Certificate (NOC) from the property owner (even if it’s you or a family member) along with a utility bill as proof of address. This is a common and cost-effective practice when you first learn how to start a business from side hustle.
3. What is the most cost-effective way to register my business in India?
A Sole Proprietorship is the most cost-effective option as it requires no formal business registration fee, and you operate under your own PAN. However, this structure comes with the significant disadvantage of unlimited liability. The next most cost-effective option is a One Person Company (OPC), which provides the benefit of limited liability with lower compliance requirements and costs compared to a Private Limited Company.
4. I am a salaried employee. How will starting a business affect my income tax?
You will need to declare income from both sources—your salary and your business—in your annual income tax return. This means you can no longer use the simple ITR-1 or ITR-2 forms. You will need to file an ITR-3 or ITR-4 form. These forms have separate sections to report “Income from Salary” and “Income from Business or Profession.” The process is detailed in our guide on Filing Tax Returns for Freelancers and Consultants. The great advantage is that you can claim all eligible business-related expenses (like internet, software, marketing) to reduce your taxable business income, which is not possible with salary income.